 Spanish
Bail Bond Payment Plans Financing California Guide
- in Bail Bond
Get Someone Out of Jail Fast — 24/7 Help
Reliable, confidential bail bonds available anytime, anywhere in California. We move quickly so you can bring your loved one home.
Get in TouchWhen a court sets bail, the hardest question is often how a family can manage the cost. A bail bond can reduce the immediate cash burden, but the payment terms still need to fit the co-signer’s circumstances. Understanding bail bond payment plans financing California starts with the premium, deposit, and schedule. That clarity is the first step toward a responsible decision.
Get an honest overview of your payment options from a licensed California bail agent
Bail bond payment plans financing in California lets a co-signer pay the premium over time instead of all at once. Espinoza Bail Bonds posts the full bond while the co-signer covers the premium, typically 10% of the bail amount, plus any agreed deposit and installments.
A licensed California agent can explain the total cost, deposit, installment schedule, and co-signer obligations before any paperwork. Clear answers matter when a loved one is in custody. Ask for every term in writing before you sign.
How Bail Bond Payment Plans Financing California Works
In California, a bail bond payment plan financing agreement splits the premium into a deposit plus scheduled installments. Espinoza Bail Bonds posts the full bond with the court while the co-signer pays the premium over time. The standard premium is 10% of the bail amount, and approval may review credit, employment, and collateral.
Many families assume the full bail amount must be paid at once. A bail bond works differently. The agent posts the full bond, while the co-signer pays the premium, which is a percentage of the total bail. In California, the standard premium is generally 10% of the bail amount. That applicable rate should be explained before you sign.
This distinction matters. For example, a $50,000 bond at a 10% premium generally requires $5,000 in premium, not $50,000 in cash. The premium is the cost of the bond. It stays separate from any collateral or other contractual requirements.
An agent cannot lower a regulated rate to create a discount. Affordability comes through a tailored payment plan. That plan divides the premium into a deposit and installments. It helps the co-signer manage the cost without delaying release.
Questions to ask before signing
- Premium: What percentage applies, and what is the total premium for the bond?
- Deposit: How much is due upfront before the bond is posted?
- Installments: What are the payment dates, amounts, and available methods?
- Security: Is collateral required, and when is it returned?
- Missed payments: What happens if an installment is late or court is missed?
Ask for every term in writing and review it with the co-signer. A clear agreement helps your family compare the immediate cost, installments, and responsibilities before moving forward.
What Does the Standard California Bail Bond Premium Cost?
The standard California bail bond premium is 10% of the total bail amount, and Espinoza Bail Bonds applies that regulated rate consistently. For a $10,000 bond, the premium is about $1,000. The premium is generally non-refundable after the defendant’s release. A licensed agent must disclose every charge and explain the rate before you sign.
California regulators require the full amount charged to be reported as the premium. A licensed agency must apply the applicable rate consistently and disclose it clearly. For example, bail set at $10,000 carries a standard premium of about $1,000. The agency posts the full $10,000 bond. The co-signer pays the $1,000 premium plus any other obligations in the agreement.
The premium is generally non-refundable once the defendant is released, even if the case later ends differently. Ask for a written explanation of every charge before authorizing the bond. A transparent quote identifies the premium separately from collateral, payment-plan terms, or other costs.
How payment plans affect the immediate cost
The premium does not have to be paid all at once in every case. A payment plan may require a deposit followed by regular installments. The structure depends on the co-signer’s finances and the agency’s approval process. Longer plans may involve a credit review, employment history, or collateral. A co-signer is often required and accepts the legal responsibility connected to the bond.
Payment plans ease the immediate burden compared with full cash bail. They do not erase the premium or change its non-refundable nature. They create a structured way to manage the cost. Digital tools can make scheduled payments easier to track.
Families comparing California bail bond financing options should focus on the total obligation, deposit, and schedule. Clear terms support better decisions during a stressful time.
When Does a Bail Bond Require Collateral or a Co-Signer?
Collateral and a co-signer protect the bond in different ways. A co-signer signs a binding contract and accepts responsibility for the agreement. Collateral is an asset pledged to secure a higher-risk bond. Espinoza Bail Bonds explains every obligation, fee, and condition in plain language before anyone signs.
Collateral and a co-signer serve separate roles. A co-signer signs a binding contract and accepts responsibility for the agreement. Collateral is an asset pledged to secure the bond when risk is higher. Neither should be a surprise.
Ask the bail agent to explain every obligation, fee, and condition in plain language before signing.
Why a co-signer may be required
A co-signer is often required when a family needs a payment arrangement. The co-signer provides accountability. They may guarantee the balance if the defendant fails to appear. That responsibility can include consequences under the bond agreement.
California law provides protections for co-signers of bail bonds. The California Attorney General explains those protections. They do not eliminate the need to understand the contract. A co-signer should review the defendant’s court obligations, the payment schedule, and what is owed if the defendant does not appear.
When collateral or a credit review enters the process
Financing decisions may review creditworthiness, employment history, and collateral. Credit checks are common for longer terms or larger amounts. Collateral may be requested in higher-risk cases. The exact requirements vary by the application. Ask for the reason and the release conditions before agreeing.
Collateral is not the same as the premium. The premium is generally earned when the defendant is released. Collateral is typically returned when the case resolves, less any amounts properly owed. Request the return process in writing, including who confirms resolution.
If you need to spread the cost over time, review the available bail bond payment plans and discuss the terms before signing.
Understanding Bail Bond Payment Plans Financing for Installments and Down Payments
Installments divide the financed portion of a bail bond payment plan into a down payment plus regular payments. At Espinoza Bail Bonds, the deposit and schedule are set during approval and confirmed in writing. Down payments may consider credit, employment, and collateral. The premium remains non-refundable even when paid in installments.
A payment plan divides the financed portion of a bail bond into an initial down payment and scheduled installments. The exact amounts and due dates are set during approval. They are not fixed at a standard rate.
Before signing, confirm the total premium, the amount due upfront, and the payment dates. Ask what happens if a payment is missed.
- Determine the premium. Confirm the bail amount and the applicable premium. Payment-plan financing does not change the amount that must be disclosed. Ask the agency to explain the total cost and which portion may be financed.
- Approve a down payment. Payment plans require an upfront deposit, then regular installments. The deposit depends on the co-signer’s finances, employment, credit, and collateral. Confirm the amount in writing and the due date.
- Set an installment schedule. The agency and co-signer set the balance, dates, and length of the plan. Choose dates that align with reliable income. If circumstances change, contact the agency before a payment is overdue.
- Make payments through an approved method. Payments may be made by phone, cash, card, or the monthly payment plan process. Espinoza also offers the BailBondPay digital portal. Save receipts or confirmation numbers after each payment.
For more on the process, read how a California bail bond works from application through release and the return of collateral.
A payment plan is a financial contract, not a promise that payments can change at any time. Review the written terms carefully. Keep communication open with the agency and ask about any fee or deadline you do not understand.
What Happens if the Payment Plan Falls Behind?
If a payment plan falls behind, the bond can be at risk, and the co-signer should contact the bail agent promptly. At Espinoza Bail Bonds, early communication helps families address missed installments before they escalate. Falling behind can lead to bond revocation or forfeiture, so the contract’s consequences matter as much as the premium.
If a co-signer falls behind, the bond can be at risk. Contact the bail agent promptly instead of letting missed payments accumulate.
A bail bond payment plan is a binding agreement. California’s Attorney General has emphasized that co-signers carry responsibilities and protections under state law. Read the California Attorney General’s guidance for bail bond co-signers and understand the documents before signing.
If an installment is missed, the agent can review the account and explain the consequences. A job loss or an unexpected expense does not cancel the obligation. Early communication gives everyone a clearer path forward.
Missed payments can put the bond at risk
Falling behind can lead to serious consequences, including bond revocation or forfeiture. The exact process depends on the contract. Falling behind is not a minor billing issue. The bond helps ensure the defendant appears in court, so the co-signer’s duty extends beyond paying.
If the defendant fails to appear, the co-signer may owe the remaining balance. Ask about court dates, payment dates, collateral, and notice requirements before signing. The contract should make clear what is expected and when.
The premium is generally non-refundable
The premium is generally earned when the defendant is released and is non-refundable. A payment plan changes when you pay, but it does not erase the premium. Review your budget realistically and complete the agreed schedule.
If circumstances change, contact your agent as soon as possible. Ask for any approved arrangement in writing. Timely payments and attention to court requirements protect the defendant, the co-signer, and the bond.
Payment Plans vs Cash Bail: Which Is Right for Your Family?
Cash bail ties up the full court amount until the case resolves, while a payment plan spreads the premium over time. Espinoza Bail Bonds helps families compare the complete obligation, not just the first payment, so they can choose the option that fits their cash and comfort.
Cash bail and a payment plan differ in how the court amount is covered. Cash bail ties up the entire amount until the case resolves. A payment plan spreads the premium over time through the bond.
The right choice depends on the cash your family can access now and how long you can leave it tied up. Paying cash may avoid the premium but requires the full amount upfront. A payment plan reduces that burden by spreading costs over time.
| Option | Upfront cost | Full amount | Refundable | Approval | Best for |
|---|---|---|---|---|---|
| Cash bail | Usually the entire bail amount | Paid directly to the court | Generally returned when court obligations are met | No financing approval, but funds must be available | Families that can commit a large amount of cash |
| Bail bond payment plan | Typically a down payment plus the first installment | The bond covers the bail, while the co-signer pays the premium | The premium is generally non-refundable after release | May consider credit, employment, collateral, and a co-signer | Families that need release without full cash upfront |
For a closer look at California bail bond payment plans, ask about the down payment, dates, refund rules, and late fees. Compare the complete obligation, not just the first payment, before you decide.
Talk to a licensed bail agent about a flexible payment plan before you arrange the bond
Frequently Asked Questions
How do bail bond payment plans work?
A payment plan divides the premium into an initial deposit and scheduled installments. The agent and co-signer agree on the terms and document the schedule before the bond is posted. The premium remains due under the contract even when payments are spread over time.
Are low down payment options available in California?
They may be available depending on the bail amount, the co-signer’s profile, and the risk of the arrangement. A lower deposit can result in larger or longer installments. Ask for the complete schedule, due dates, and any collateral requirements before signing.
Does my credit score affect eligibility for financing?
It can, especially for a longer term or a larger premium. Approval may also consider employment, income, and collateral. The agent should explain what information is needed and which terms you qualify for.
What is the co-signer responsible for?
The co-signer enters a binding contract and is generally responsible for the balance if the defendant fails to appear. California provides protections, but they do not remove the contract’s obligations. Review every condition, including payment and court-appearance requirements, before signing.
Is the bail bond premium refundable after release?
Generally, no. The premium is earned when the defendant is released. Payment plans change when you pay, not whether the premium is owed. Confirm the written terms with the licensed agent and keep records of every payment.
Ready to Discuss a Payment Plan?
Understanding your options makes the bail process easier to manage. A licensed California agent can review your situation and explain available payment arrangements. Ask about the next steps and what information you will need.
Contact us today to talk with a licensed California bail agent about flexible payment plans
About the Author
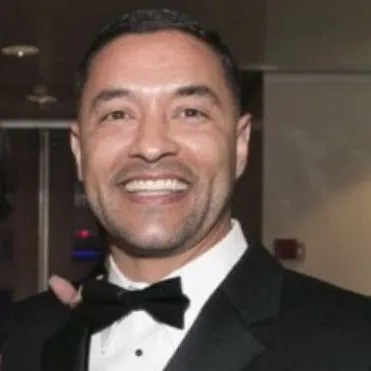
Jose F. Espinoza
Licensed Bail Agent #1841969 · Founder, Espinoza Bail Bonds
Jose F. Espinoza is a U.S. Army veteran, former Military Police officer, and licensed bail agent who founded Espinoza Bail Bonds in 2014. After 25 years of decorated military service, he now brings the same discipline, loyalty, and calm leadership to helping families navigate the bail process. Jose believes in second chances and treats every client with dignity, respect, and compassion.

 Speak to a Bail Agent:
(844) 325-8424
 Request a Callback: Call
Me
Now!
 Other Options:
Contact Us